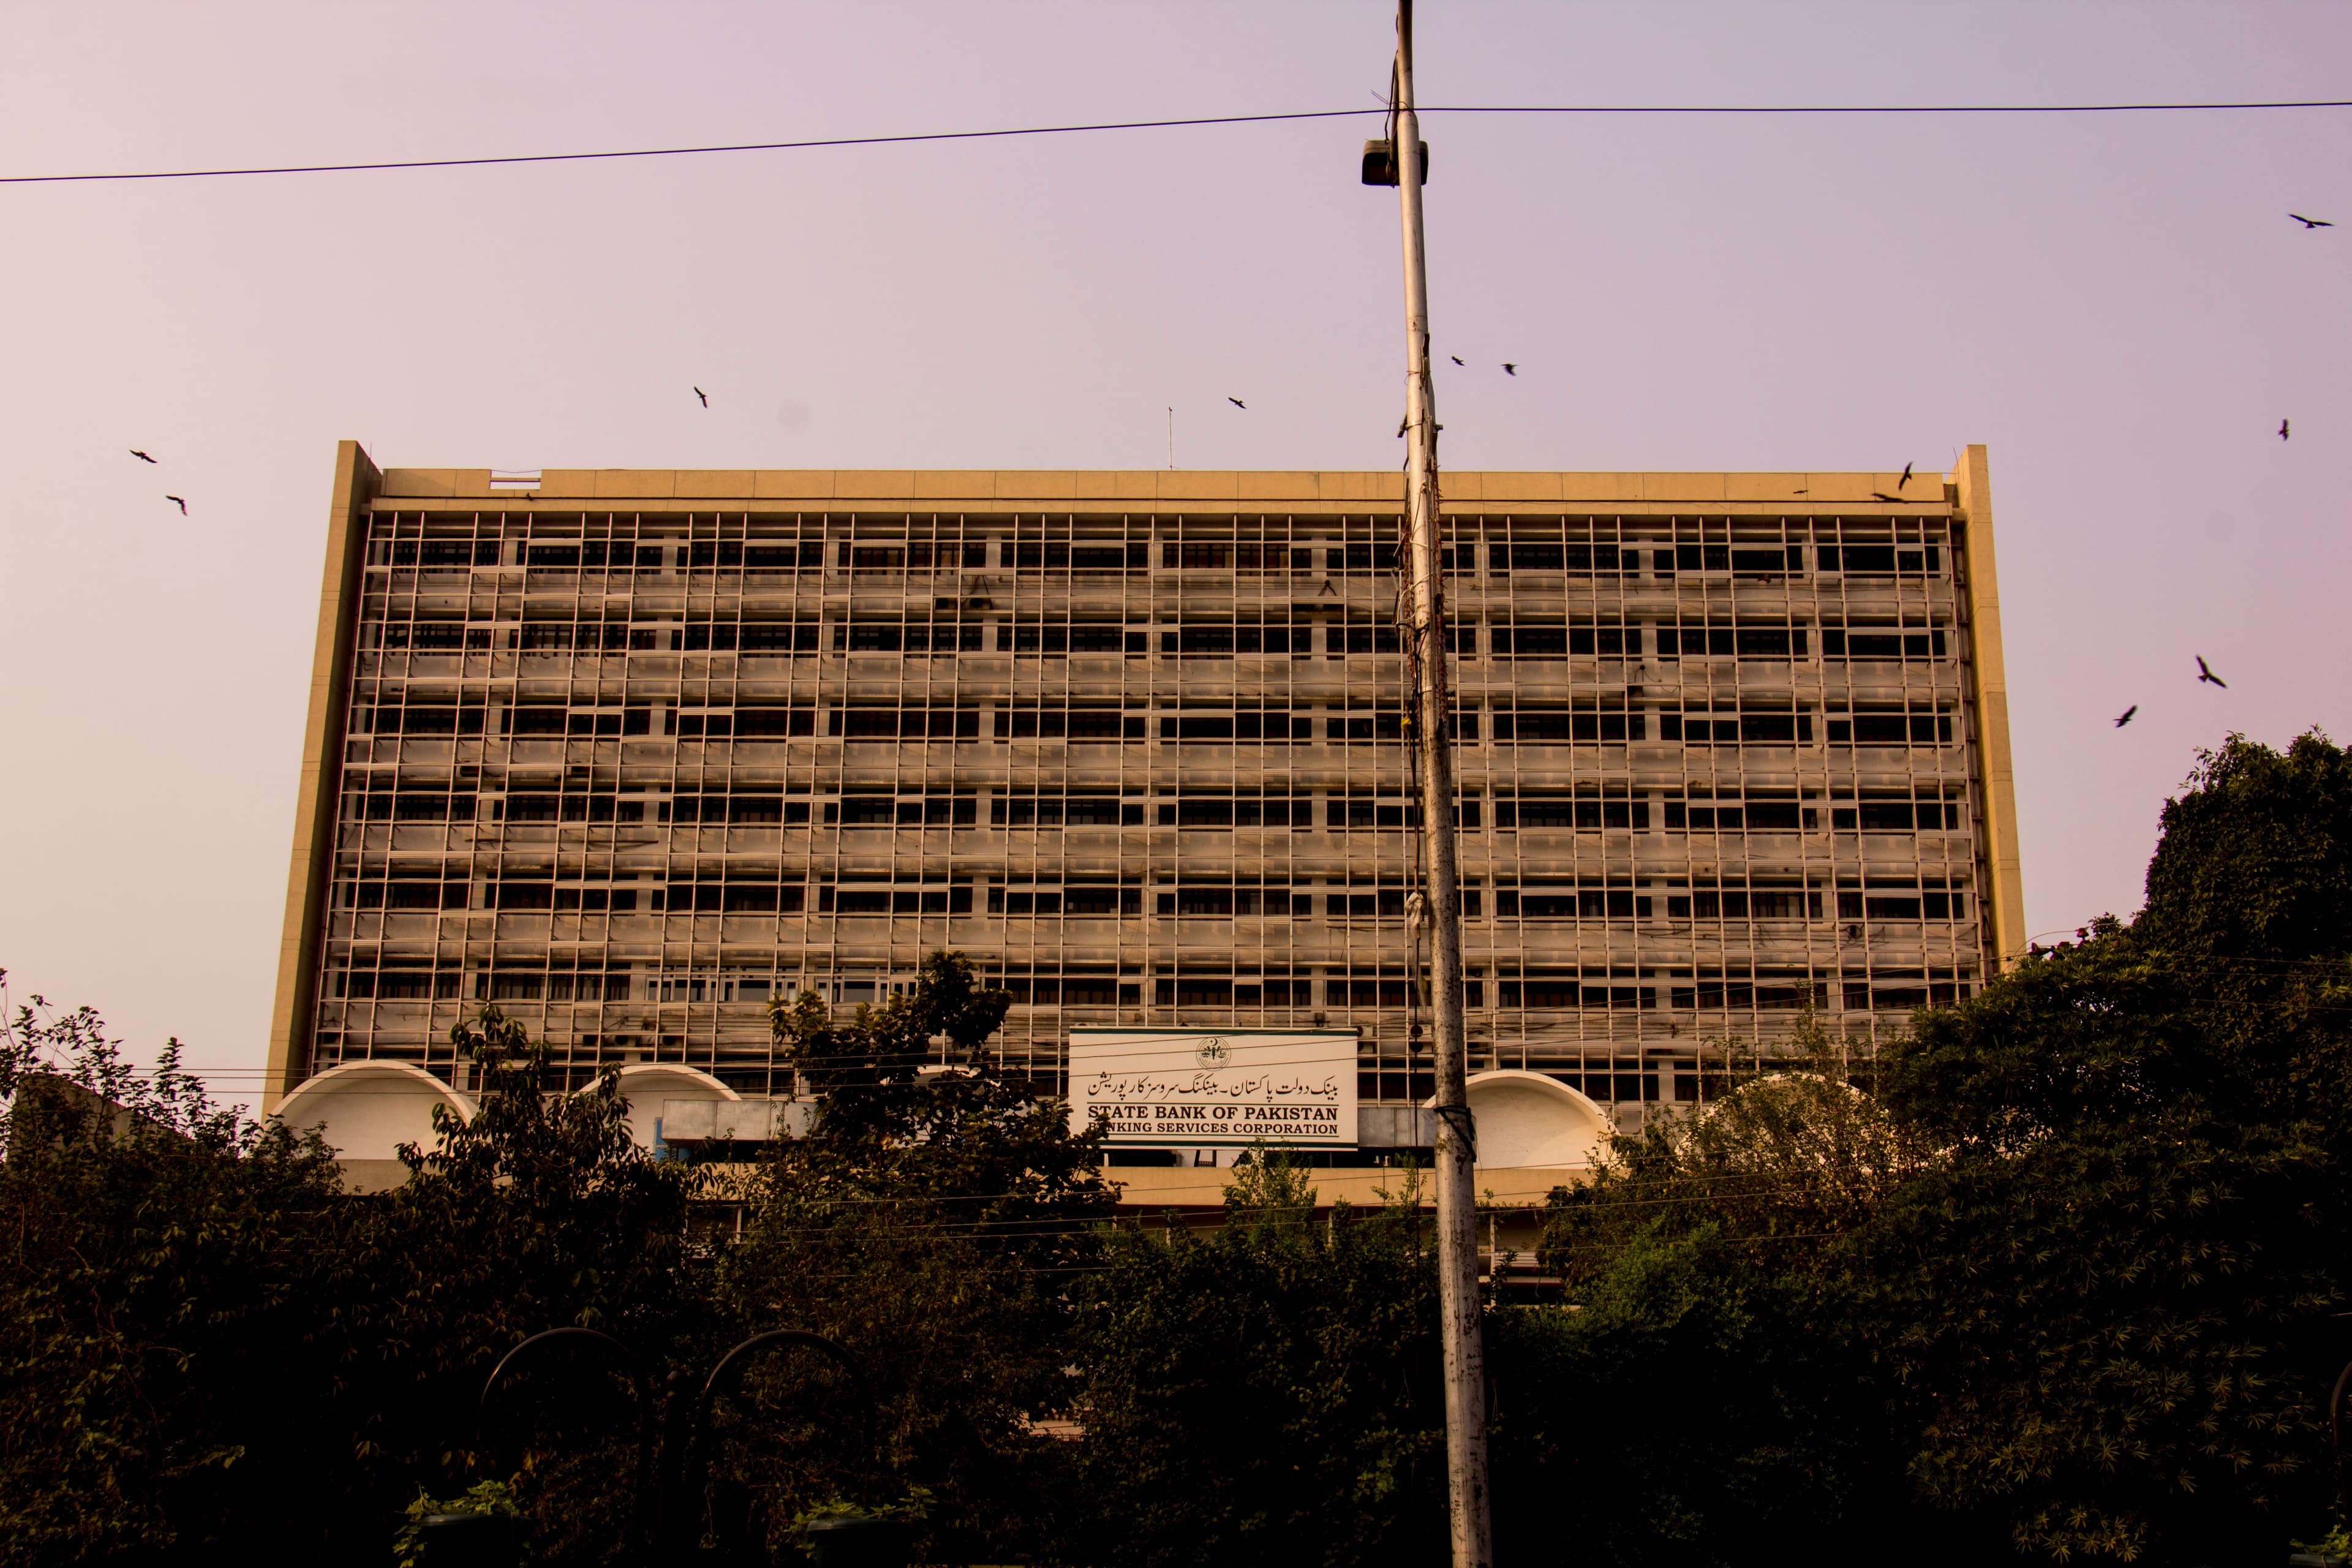
Pakistan sells a record $3 billion Eurobond after successive credit upgrades
Islamabad placed $1.75 billion of 5.5-year notes at a 7.5 percent coupon and $1.25 billion of 10-year notes at 7.9 percent. The book reached nearly $6 billion. It is the first large issue under a renewed GMTN programme.
Islamabad3 min read
Last updated
Pakistan raised $3 billion in a two-part dollar Eurobond on 2–3 September, the Finance Ministry said, calling it the country’s largest single transaction in the international capital markets. Orders came in at nearly $6 billion, about twice the amount sold.
The deal split into a $1.75 billion note with a 5.5-year tenor and a 7.5 percent coupon, and a $1.25 billion 10-year note at 7.9 percent. Those coupons sit below the 8.25 percent rate on a long-dated Pakistani Eurobond issued more than a decade ago under a previous PML-N government, a bond that has already been repaid.
Bloomberg, citing people familiar with the pricing, put the yields at 7.75 percent on the five-year piece and 8.25 percent on the 10-year piece. The ministry statement used coupon language. The gap is the usual difference between the printed coupon and the yield at which the notes actually cleared.
What the book actually showed
The Finance Ministry said the order book came from a “broad and diversified base of institutional investors across global markets and continents.” Demand reaching the 10-year tenor mattered more to the desk than the headline size. Pakistan has often been able to sell short paper. A 10-year bid of this scale is the signal investors were pricing a longer horizon.
Joint lead managers and bookrunners named earlier in the process were Citigroup, Deutsche Bank, Emirates NBD Capital, MUFG and Standard Chartered. The notes sit under a 144A/Reg S format on a Global Medium-Term Note programme that Pakistan reconstituted in July. The ministry called this sale the first issuance under that renewed GMTN platform.
It is not the first dollar print of 2026. In April, Islamabad sold a three-year Eurobond that started at $500 million and rose to $750 million after a $250 million green-shoe. That note carries a 6.975 percent coupon and matures in April 2029. In May the government sold a debut three-year Panda bond of 1.75 billion yuan, then about $250 million. A $1.4 billion Eurobond was repaid in April.
Why the window opened
The mandate went out a week after Moody’s lifted Pakistan to B3. S&P and Fitch had already moved the sovereign to single-B territory; S&P raised it again, from B- to B, in July. Finance Minister Muhammad Aurangzeb had said a return to the G3 currency markets depended on those upgrades.
Adviser Khurram Schehzad announced the dual-tranche process on 2 September. Budget papers for fiscal year 2026-27 had flagged about $2 billion of international bonds. The book allowed a larger print.
Officials speaking to Pakistani newspapers before the sale said part of the point was to replace shorter bilateral deposits from China and Saudi Arabia that Islamabad has had to roll, with formal requests, every few months. The ministry statement did not name those deposits. It did say the aim was “active sovereign liability management”: diversify sources, extend maturities, cut rollover risk, and, where the arithmetic works, swap shorter and dearer debt for longer paper at a competitive price.
“This is the difference between simply borrowing and actively managing the sovereign balance sheet,” the statement said.
What the coupons do not settle
A $3 billion issue does not, by itself, change the external-debt schedule. It does give the government a market quote on five- and ten-year risk after three years of rating repair. That quote will now sit on screens for the next tap.
Investors who doubled the book were buying a B-rated credit in a week when West Asian fighting had already lifted oil and risk premia elsewhere. The 10-year coupon of 7.9 percent is the price they accepted for that mix of improved ratings and residual political and external risk.
The next test is mechanical. If the proceeds retire dearer or shorter claims, the duration of the stock improves. If they fund the current account, the next GMTN print will face the same refinancing question at a new set of yields. The ministry has now put both outcomes on the record as policy. The bond market will score them on the next call.
Continue reading
 Sports
Olise scores, Bastoni answers, and France draw Italy 1-1 in Zidane's home debut
Almanaque Digital DeskSaint-Denis
- News
Sudan's army says it has taken al-Mazroub, the RSF's main North Kordofan base
Almanaque Digital DeskKhartoum
- News
Lalremsiami's tenth-minute shot gives India hockey gold and an LA 2028 place